Showing posts with label Protasco. Show all posts

Tuesday, 23 September 2014

Protasco: Conspiracy & Secret Money?

As a new shareholder in Protasco for less than a month, it is shocking for me to learn that Protasco has filed a legal suit against two of its directors, as well as PT ASU.

Protasco sues PT ASU in order to claim back its deposits paid earlier and damages arising from the collapsed Oil & Gas deal. This means that Protasco has real difficulty in getting back the deposits paid, which is RM50mil (RM71.9mil according to CIMB).

The two directors Tey Por Yee & Ooi Kock Aun are non-executive directors. They are major shareholders in Protasco as well, at 17.7% and 3.74% respectively (from Annual report 2013).

Both are them are alleged to have committed conspiracy to defraud Protasco & making secret money out of it!

So, there is an apparent disharmony within Protasco's board. The failure to settle this issue internally might indicate its severity.

Other than the attractive dividend yield, I bought Protasco because I am optimistic of its property & construction arms. I predict that it can potentially post a surprise jump in profit in the next 1-2 years.

It is hard for outsiders to guess what has actually happened in this aborted O&G deal. The credibility and capability of its directors are put to serious test for sure.


How will this legal suit affect Protasco?

Will Protasco's fundamentals seriously affected? I don't think so.

Will the construction progress of DeCentrum & PPA1M affected? I don't think so.

Will it affect its property take-up rate? I don't think so.

Will it affect the award of new contracts from government? I don't think so.

Will it affect student enrollment at IUKL? I don't think so.

Will it affect its overall revenue in FY14? I don't think so.

Will it affect its net profit? Yes, there will be an impairment loss if it can't claim back the deposit. However, I'm not sure in which quarter this will be registered. The amount of RM50mil (or RM71.6mil) is huge!

Will it affect its current cash flow & balance sheet? I think it won't, as cash has already been paid earlier, and impairment loss registered later should be a non-cash item. Anyway, it's still a loss of cash amounting to 15sen (or 21sen) per share.

Will it affect the dividends payout? I think more or less it will. Investors might still get good dividend but it can be better if 15sen (or 21sen) per share is not lost.

Will it claim back the deposit eventually? I don't know, but I think it should be able to do so, though it may take a long time.

Are the management of Protasco credible? I don't know, but this should be the most important aspect for long term investors. There are comments that this O&G deal was not transparent from the beginning. Either the carelessness or dishonesty of directors is to be blamed. Anyway this company is generous enough to give high dividend payout.

All these are just my personal opinion which might not be true.

So, should investors sell at all cost or accumulate at this rare opportunity? Well, as usual, you make your decision at your own risk.

Wednesday, 3 September 2014

Why Protasco?

Last year I did not want to buy Protasco's shares at RM1.40, but now I bought them at RM1.64!

When I started to study Protasco last year, its share price was hovering around RM1.40.

Apart from the fact that it depends on government for contracts which I don't really like, I think it is still a good company to invest in, as it diversifies its earnings into property & Oil & Gas sector.

At that time, I decided that I will only buy Protasco if its share price drops to RM1.20 or below.

In the end, it turned out that Protasco's share price advanced 50% from RM1.40 all the way up to RM2.10.

I thought that I will never have a chance to be a shareholder in Protasco, just like what I experienced earlier with Boilermech & BJ Auto.


However, due to the cancellation of O&G deal, and perhaps disposal of shares by major shareholder & director, Protasco's share price fell all the way down from RM2.10 to current level of around RM1.65.

I was aware that its share price was falling but I did not really keep a close eye on it, until one day it just happened by chance that I noticed it has reached its major support line at RM1.65 on 15/8/2014.

I have a strong feeling: Is it my second or perhaps last chance to own Protasco?

So I bought its shares at RM1.64 on 15/8/2014, at 12:29pm just a few seconds before market afternoon break.

Never had I felt so lucky because after the market re-opened 2 hours later, straight away Protasco jumped and closed at RM1.69. It even breached RM1.80 in the next 2 days.

However, it has fallen back to my entry level now. Luck is running out? Or third chance to accumulate more?


Why I bought Protasco? There are actually multiple reasons.


1. Growth in property & construction division

Protasco launched the first phase of its DeCentrum project in Bangi in the end of year 2012. It's been almost 2 years so I would expect it to contribute more to its top & bottom lines from now on, though the overall GDV is not too high at RM250mil.

Just recently in June 2014, Protasco has launched the phase 2 of DeCentrum, which is Unipark condo (2x20 storey towers with 320 units) with GDV of RM225mil. It was reported that 50% were snatched up in the first week. So this should contribute positively to its FY14Q3 result I guess.

This 100-acre RM10bil DeCentrum project is 100% owned by Protasco.

Protasco has purchased 14.4 acres of commercial land in Pasir Gudang. Earlier MIDF reported that it may launch phase 1 with GDV RM800mil next year. However, in anticipation of softening property market next year, Protasco is looking to slow down its launch in the near future.

Besides, Protasco has entered into an MoU on 28/5/14 to joint-venture with Nextnation (Nexgram) to develop a 5.9-acre mixed development in Cyberjaya. Both parties share similar shareholder in Tey Por Yee & Ooi Kock Aun. The MoU will expire in 6 months.

For the construction part, the excitement is the RM578.5mil  PPA1M Civil Servants housing project at Putrajaya awarded on 23th Oct last year. It is expected to be completed in 2 years so it might also contribute greatly from the second half of FY14 onward.

Meanwhile, the two PR1MA projects worth RM88mil at Manjung & Jelebu have been delayed due to land issue.


       Phase 2 of DeCentrum - Unipark Condo


2. Attractive dividend yield

Even though at RM1.65, Protasco's PE ratio is not that low, but its dividend yield is certainly excellent at 6%.

I think this dividend yield can support its share price above RM1.65. As I expect its bottom line to grow in the next 2 years, this means that dividend paid to shareholders will increase as well, as long as it keeps its generosity in dividend payout at 50-60%.


FY Net Dividend / Share (sen)
2009 9.0
2010 10.0
2011 8.0
2012 14.0
2013 10.0
2014 ??


3. Strong balance sheet

In short, it is in a net cash position. Cash flow from operation in FY13 was very good but it is in the negative territory after the second half of FY14, mainly due to decrease in payables.

This may not sound nice but I find that Protasco usually has negative operating cash flow in mid year, and it will turn positive at year end may be due to the billing nature of its contracts. Protasco never fail to end its financial years with positive operating cash flow since listed in 2003. So I expect it to turn positive by year end.


4. Failure in O&G venture

For me, the inclusion of O&G business will make Protasco complicated and hard to predict. It may need to pump in a lot of money. So it's not the end of the world after the deal fell through, as Protasco will concentrate more on its core businesses.


5. Falling share price.

If Protasco is still trading at RM2.00 or above, I will not consider to buy. However, it fell to a strong support with dividend yield of at least 6%.


       Protasco @ RM1.65


Anyway, there are some issues that need to be taken into account.

As we all know, a big chunk of Protasco's income comes from road maintenance contracts, which is recurring in nature.

However, some of the long-term contracts are expiring soon as shown in the table by MIDF below.


MIDF reported that Protasco is currently negotiating for renewal of road maintenance contracts. MIDF is confident that Protasco will be awarded the renewal contract by the end of 2014. If it fails, then the attractiveness of Protasco will be greatly discounted.

The award of building construction is on negotiation basis, and the contracts may not come regularly. So this might mean fluctuation in financial contribution from construction division.

So far the contracts awarded to its construction division this year include:
  • 21/1/14 - Projek Perumahan Mampu Milik 1Malaysia in Manjung & Jelebu, in 18 months from date of sites possession, RM88.1mil
  • 2/6/14 - Federal road zone 2A Sarawak, in 12 months, RM21mil
As stated earlier, the PR1MA projects are still yet to kick off due to land issue. 

In Mac 2014, Protasco has also signed agreement with Himalayan Builders & Engineers to invest USD100mil to set up engineering testing lab (memorandum of collaboration) & boutique hotel (MoU) in Nepal. At the same time, an agent will promote and enroll Nepalese students to IUKL.


       Beautiful Nepal


Protasco has proposed private placement of 50 million new shares together with 1:2 free warrants, as well as bonus issue of 1 free warrant for 10 existing shares. Total warrants issued will be 133.5mil. This exercise will increase the total paid-up share by a whopping 54.8% to 518mil if all warrants are converted to mother shares in the future.

Since the O&G venture has failed, I think Protasco's small shareholders should pray very very very hard that this corporate exercise will be called off.

Thursday, 13 February 2014

Losing Steam In Protasco

About 2 weeks ago, Protasco announced the amended SPA of its Oil & Gas venture with PT ASU.

Refer this link for the original version.

After the amendment:

- Acquisition of 76% in PT ASI is reduced to 63%
- Indirect 50.5% stake in PT Haseba is reduced to 42%
- Purchase price of USD55mil is reduced to USD22mil
- Four-year PT ASI PBT guarantee of USD50mil is reduced to USD22mil

The 4-year PBT guarantee is progressive by years


The profit guarantee is for PT ASI. Protasco only have 63% stake in PT ASI now. So for Protasco, it is guaranteed to get USD13.9mil or RM45.7mil (exchange rate 3.3) in the first 4 years.

Even in year 2017, when the profit guarantee per year is USD9mil or RM29.7mil, Protasco is only guaranteed to get PBT at least RM18.7mil. This is only 18% of its FY2012 total PBT.

Initially I'm very excited on Protasco after I found out that PT Haseba made RM95mil profit after tax in FY2009. This translates into RM63mil PAT in a single year for PT ASI (ASI owns 66.5% in Haseba).

If you compare RM63mil PAT in a year to RM73mil PBT (USD22mil) in 4 years, there is a lot of difference.

The reality is, where got so many big frogs jumping all over the street?

It is also not a good sign if a company's profit forecast is reduced...

However, there is an agreement like this in the restated SPA:


It seems like there is a targeted production in the agreement (7.2mil barrels of oil & 44.2bil cubic feet of gas), in which after the targeted production is reached, Protasco will have 100% of PT ASI, or 66.5% PT Haseba.

Do I interpret it correctly? ( I have to admit that I'm too lazy to read the whole document)


I have no idea how long this targeted production can be reached, but this seems to be very positive for Protasco in long term.

I assume that it should be at least after the 4-years profit guarantee then only the targeted production can be reached. As we can see from the progressive nature of  its guaranteed profit, PT ASI's profit is expected to increase year by year. 

When Protasco has 100% PT ASI, and if PT ASI posts USD10mil net profit in year 2018, then it will be RM33mil net profit for Protasco in 2018 from its O&G segment alone. 

For comparison, Protasco's whole year FY2013 net profit should be RM40mil+. This looks attractive, doesn't it?

However, this will be many years later...


It is fair that Protasco gets less profit guarantee with less purchase price. However, I'm still feeling slightly disappointed with this new deal. 

I don't mean that Protasco is a bad company. It's just that I am a bit disappointed with its O&G venture which drew my interest to the company in the first place, or else I don't usually like companies that depend heavily on government for contracts.

I expect greater and faster contribution from its O&G venture, but it turns out to be rather slow.

However, Protasco's property arm can still carry the company forward in the near future. Its O&G segment certainly has a great potential, but might take a while to produce wonder.

Thursday, 16 January 2014

Protasco: Seeking A Breakthrough

Protasco Berhad recently proposed a private placement of 50mil new shares which comes with 2 free warrants each, plus a bonus warrant of 1 free warrant for every 10 ordinary shares.

The placement shares represent 15.93% of current total shares while total warrants issues will be 100mil + 33.5mil = 133.5mil.

The exercise price of warrants is proposed at RM2 with an exercise period of 5 years. If all the warrants are converted into shares, Protasco's total shares will reach about 539mil (including ESOS, & treasury shares), compared to 332mil shares at the moment.

This represents a dilution of about 62%. Will Protasco's net profit attributed to shareholders increase by at least 62% in 5 years time?


Protasco is a diversified group with businesses in:
  • Maintenance
    • Road maintenance service
  • Construction
    • Construction of new roads & building
  • Engineering service
    • Road, traffic & construction related
  • Education
    • Infrastructure University Kuala Lumpur (IUKL)
  • Trading
    • Construction related materials
  • Property

The maintenance segment is Protasco's bread & butter in which for its first 9 months of FY2013, 60% of revenue and 98% of PBT come from this segment.


For 9MFY13, Protasco's revenue and profit after tax & minority interest increases by 20% (RM484.0mil to RM581.7mil) and 7% (RM30.7mil to RM32.8mil) respectively compared to previous year's corrsponding period.

It is not easy to predict Protasco's FY13Q4 results as its quarterly performance fluctuated a lot historically. 

Nevertheless, I believe Protasco's PATAMI can reach at least RM42mil for FY2013. This represents an improvement of 12% from RM37.5mil in FY2012. 


       Protasco's financial performance 2008-2012

At this earning level and current total shares of 332mil, EPS will be 12.7sen. If we give a fair PE ratio of 10x, then the target price will be RM1.27. Currently Protasco is trading at RM1.42, with a forward FY13 PE of 11.2x.

In other words, Protasco's share seems not very undervalued at RM1.42.

If Protasco's share base is to be increased by 62% in 5 years time, can its PATAMI increase 62% as well to RM68mil in the same period of time?

       Maintenance work

While the maintenance and construction arms continue to contribute recurring and consistent profit, Protasco's "62%" increase in earning may depend on:
  • Property development
  • Oil & Gas

Property

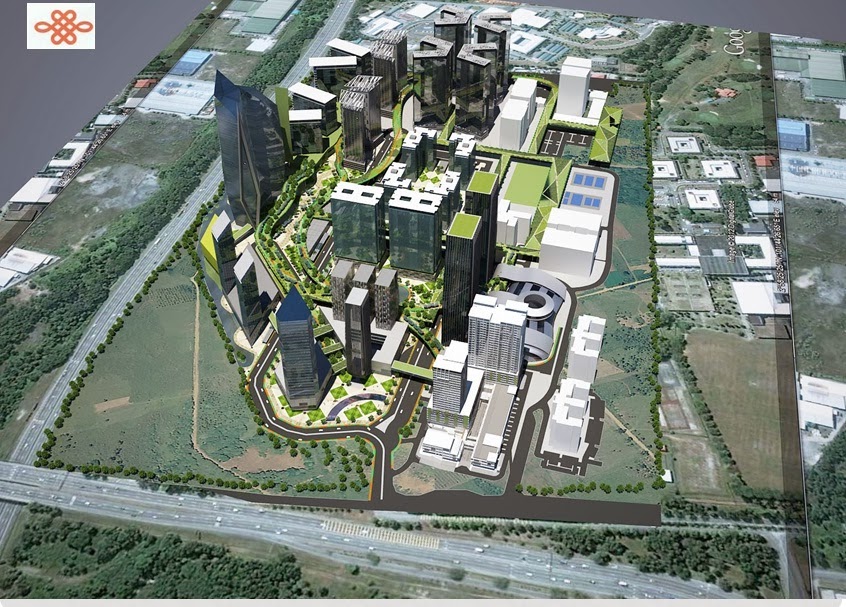
Protasco has completed its maiden property project Unipark Condominium in Kajang in 2012. Currently it is working on its second property project on the same site - De Centrum City, which sits on a 100-acre land which includes IUKL in Kajang.

The whole project is worth about RM5bil and will take 10-15 years to complete.

Phase 1 of De Centrum City, known as De Centrum with a GDV of RM239mil will take up only 4.6 acres of the land and was launched in 2012. It comprises 192 units SOHO, 320 units serviced apartments, 60 units 3-storey shoplots and a 3-storey mall with an NLA of 76,000 sq ft.


       De Centrum, Kajang

From internet search, currently the construction progress is only on ground level for the 12-storey SOHO (on 3-storey mall) & 20-storey apartments (on 8-storey car park & 1-storey facility floor).

From the circular to shareholders in relation to the private placement, the management mentions a proposed development of 2 blocks (Block C & D of De Centrum) of 20-storey apartments comprises 240 units apaerments & 80 units duplex with a GDV of RM130mil (cost RM117mil). It is expected to commence in Q2 FY14 and might be part of the phase 2.

De Centrum City may be more resistant to property slow down as it has great location. It is surrounded by IUKL, UPM & UniTen, and is at the junction of KL-Seremban Highway, SKVE, SILK and Besraya Highway. 

       De Centrum City: at the junction of major highways

       De Centrum City Masterplan

According to its MD Dato Sri Chong KP, Protasco is looking to increase property contribution to 10-15% of group profit in 3-5 years time (currently 5%), and targeting a minimum of 40% contribution in the long run.

The management has acted on its words by acquiring a 14.4 acres leasehold land in Pasir Gudang from JCorp through its 64% owned subsidiary Sun Rock Development for RM22.5mil. Protasco plans to develop the land into a mixed development which carries a GDV of RM505mil. The development should start after 2015.


Oil & Gas

Protasco has announced its proposed venture into oil & gas sector since December 2012. It was initially expected to be completed by 2013 but has been delayed.

From the proposed acquisition, Protasco will acquire 95 million shares or 76% of PT Anglo Slavic Indonesia (ASI) from PT Anglo Slavic Utama (ASU) for USD55mil (RM170.5mil).

PT ASI was incorporated in Indonesia on 6 Sep 2012 and is involved in oil & gas assets investment. PT ASI holds 95% of PT Firman Andalan Sakti (FAS), which holds 70% of PT Hase Bumou Aceh (Haseba).

The jewel here is PT Haseba, who has been granted rights by PT Pertamina (state-owned) to develop and produce O&G in Kuala Simpang Timur field at Nanggroe Aceh Darussalam Province, Indonesia. However, the 10-year agreement from 14 Dec 2004 will expire in the end of 2014. PT Haseba is understood to be in negotiation with Pertamina for an extension.

So, Protasco will have 0.76 x 0.95 x 0.70 = 50.54% stake in PT Haseba.

For its FY2009 ended Dec09, PT Haseba registered a PAT of RM95mil out of a revenue of RM274.0mil. However, I'm not sure what kind of corporate exercise was done as it suffers total RM237mil loss in 2010 & 2011 with almost zero revenue.

If PT Haseba is to maintain its FY2009 performance after Protasco acquisition, then it will be 95 x 0.5054 = RM48mil net profit a year to Protasco, which is higher than its overall estimated PATAMI of FY2013!

However, PT Haseba's profit is hard to predict at this stage.


In the agreement of acquisition, a profit before tax guarantee of USD50mil (RM155mil) in 4 consecutive financial years is given for PT ASI by PT ASU. By average, this would be RM39mil PBT a year.

As Protasco will own 76% of PT ASI, it will be RM29mil average annual PBT for Protasco. This figure is close to Protasco's FY13Q3 single quarter PBT of RM30.4mil.

With the contribution from future O&G and property segment, Protasco should be able to increase its PATAMI by at least 62% discussed above. With the management's ambition to become a prominent property player, the future earning prospect of Protasco is quite impressive.

Thus, even though all warrants are converted into shares in 5 years, Protasco should be able to provide a higher EPS compared to now.

For its bread & butter business, Protasco has secured a few contracts in the past one year.

  • Dec 2012 - maintain roads in Perak for 7 years, RM29.6mil for first 2 years
  • May 2013 - upgrade roads in Kedah in 9 months til Feb14, RM37mil
  • Jun 2013 - construct roads in Johor in 12 months, RM50.4mil
  • July 2013 - maintain roads in Sarawak, RM23mil
  • Oct 2013 - construct 1680 apartment units in Putrajaya in 24 months for 1M Civil Servants Housing Programme, RM578.5mil

For the construction contract in Putrajaya, it is mentioned that the development cost is RM520mil. So perhaps it is roughly a PBT of RM58mil in 2 years or RM29mil a year, which should contribute massively to the group.

Besides, IUKL has been upgraded to full-fledged university status since Sep 12. With better academic status and the development of De Centrum City, IUKL might attract more students in the future.


       Historty of IUKL


Protasco is currently in net cash position after a private placement in early 2013. At 9MFY13,

  • Cash & bank balances: RM56.3mil
  • Deposits with license banks: RM67.6mil
  • Short term borrowings: RM43.3mil
  • Long term borrowings: RM4.0mil
  • Bank overdraft: RM13.9mil
Net cash = RM62.7mil

However, after the acquisition of Oil & Gas company and Johor land, its cash is expected to diminish quickly. That's why it is calling for another private placement and warrants.

For FY2012, Protasco gave away 8 sen dividend + special dividend 6 sen, altogether 14sen single tier. This represents a mouth-watering 10% yield at RM1.40.

I think investors can expect at least 8-10sen net dividend for FY2013, which is 5.6%-7% yield if you buy the share at RM1.42. So far 4sen has been paid.

Thus, Protasco is another company with both good dividend and growth potential.

       MD & founder Dato Sri Chong Ket Pen


Back to the proposed private placement & free warrants, the placement share price is at least RM1.65 and the warrant exercise price is at RM2. Both are significantly higher than current share price of RM1.42.

Does this mean that Protasco is at least worth RM1.65 in 2014?

I've been waiting for Protasco's share price to drop to my desired level for the last 3 months but apparently it doesn't happen, and will never happen I guess, especially when the O&G acquisition is finalized probably in the first quarter of 2014.