Showing posts with label Matrix. Show all posts

Friday, 4 September 2020

My Portfolio Aug20

Summary For Aug 2020

Aug-20
Numbers of stocks 13
Share Sold Matrix @ 1.74


Share Bought Genetec @ 1.49

Supermax @ 21.30
Overall 2020
Portfolio Return Aug20 13.41%
KLCI Return Aug20 -4.90%
Portfolio Return YTD20 28.34%
KLCI Return YTD20 -4.00%


Portfolio @ End of Aug20

Stocks Avg Jul20 Aug20 Div20 Aug20% Overall%
BAUTO 1.92 1.41 1.36 4.2 -3.5 -29.2
DAYA 0.035 0.015 0.020
33.3 -42.9
GENETEC 1.49
1.520

2.1
HIBISCUS 1.05 0.60 0.595
-0.8 -43.3
JAKS 0.88 0.77 0.76
-1.3 -14.2
JHM 1.33 1.52 1.69
11.2 27.1
KPOWER 2.03 2.60 3.27
25.8 61.5
KRONO 0.76 0.570 0.600
5.3 -21.0
LEONFB 0.505 0.305 0.315
3.3 -37.6
PRLEXUS 1.15 0.64 0.685
7.0 -40.4
SCIB 2.06 2.83 3.42
20.8 66.0
SCIENTEX 2.735 9.10 9.40 10.0 3.3 243.7
SUPERMAX 21.3
22.14

3.9


In August, finally I sold all my Matrix shares after holding them for almost 7 years. The gain of 76%, or average 11% per annum is not too bad.

Matrix is the stock that I always want to sell but also reluctant to sell. I might decide to sell tonight but the next day I change my mind. This scenario repeated multiple times.

There is another stock more or less like this and it's Scientex. At this point of time I plan to keep it for long term until a drastic change to its fundamental.

I added Genetec and Supermax in August. The strategy in Genetec is similar to Geshen, a loss-making company which has a potential to turnaround. 

Monday, 6 July 2020

My Portfolio Jun20

Summary For June 2020

Jun-20
Numbers of stocks 14
Share Sold Notion @ 0.705 (all)
Share Bought JAKS @ 0.88

JHM @ 1.33

SCIB @ 2.06 (add)
Overall 2020
Portfolio Return Jun20 2.83%
KLCI Return Jun20 1.88%
Portfolio Return YTD20 -0.50%
KLCI Return YTD20 -5.53%


Portfolio @ End of June 2020

Stocks Avg May20 Jun20 Div20 Jun20% Overall%
BJAUTO 1.92 1.25 1.48 4.2 18.4 -22.9
DAYA 0.035 0.005 0.010
100.0 -71.4
DKSH 2.50 2.83 2.49
-12.0 -0.4
GESHEN 0.43 0.44 0.43
-2.3 0.0
HIBISCUS 1.05 0.56 0.62
10.7 -41.4
JAKS 0.88
0.86

-2.3
JHM 1.33
1.34

0.8
KPOWER 2.03 1.98 2.30
16.2 13.6
KRONO 0.76 0.52 0.535
2.9 -29.6
LEONFB 0.505 0.315 0.310
-1.6 -38.6
MATRIX 1.42 1.70 1.81 6.00 6.5 27.5
PRLEXUS 1.15 0.65 0.54
-16.9 -53.0
SCIB 2.06 2.03 2.13
4.9 3.4
SCIENTEX 2.735 8.28 8.90
7.5 225.4


For June 2020 my portfolio achieved a modest gain of 2.8%. Year-to-date it's close to break even.

On 29th May, I bought  my first stock since February this year. I'd say it's quite late and there are a lot of opportunities missed.

My first purchase was KPower followed by SCIB on the same day. In early June, I increased my position in SCIB and added Jaks into my portfolio. Only in late June I decided to add JHM.

My confidence in current stock market was actually not that high, so I was thinking of whether I should invest short term "hit & run" style or mid to long term like I used to do.

I decided to choose the latter.

As mentioned in my previous articles about Jaks, I believe that Jaks's FY21 will be great. However, as this stock has bad "Qi" from its history, it might not go up to where everybody wants it to be in a short period of time.

Jaks, together with Datuk Abdul Karim's KPower & SCIB are all companies in construction sector, a sector which is not in positive trend like health-related and technology stocks. 

Nevertheless, they are not in negative trend either. It's just neutral. Upcoming 12th Malaysia Plan (2021-2025), along with Sarawak state election and possible snap GE15 might act as catalyst for construction sector.

There are many tech stocks that I wish to invest in, including MI, SAM, Frontken, JHM & Gtronic. Finally I selected JHM mainly because I feel that its business model and products have the potential to generate good growth going forward, even though its share price has already went up more than 10 times before.

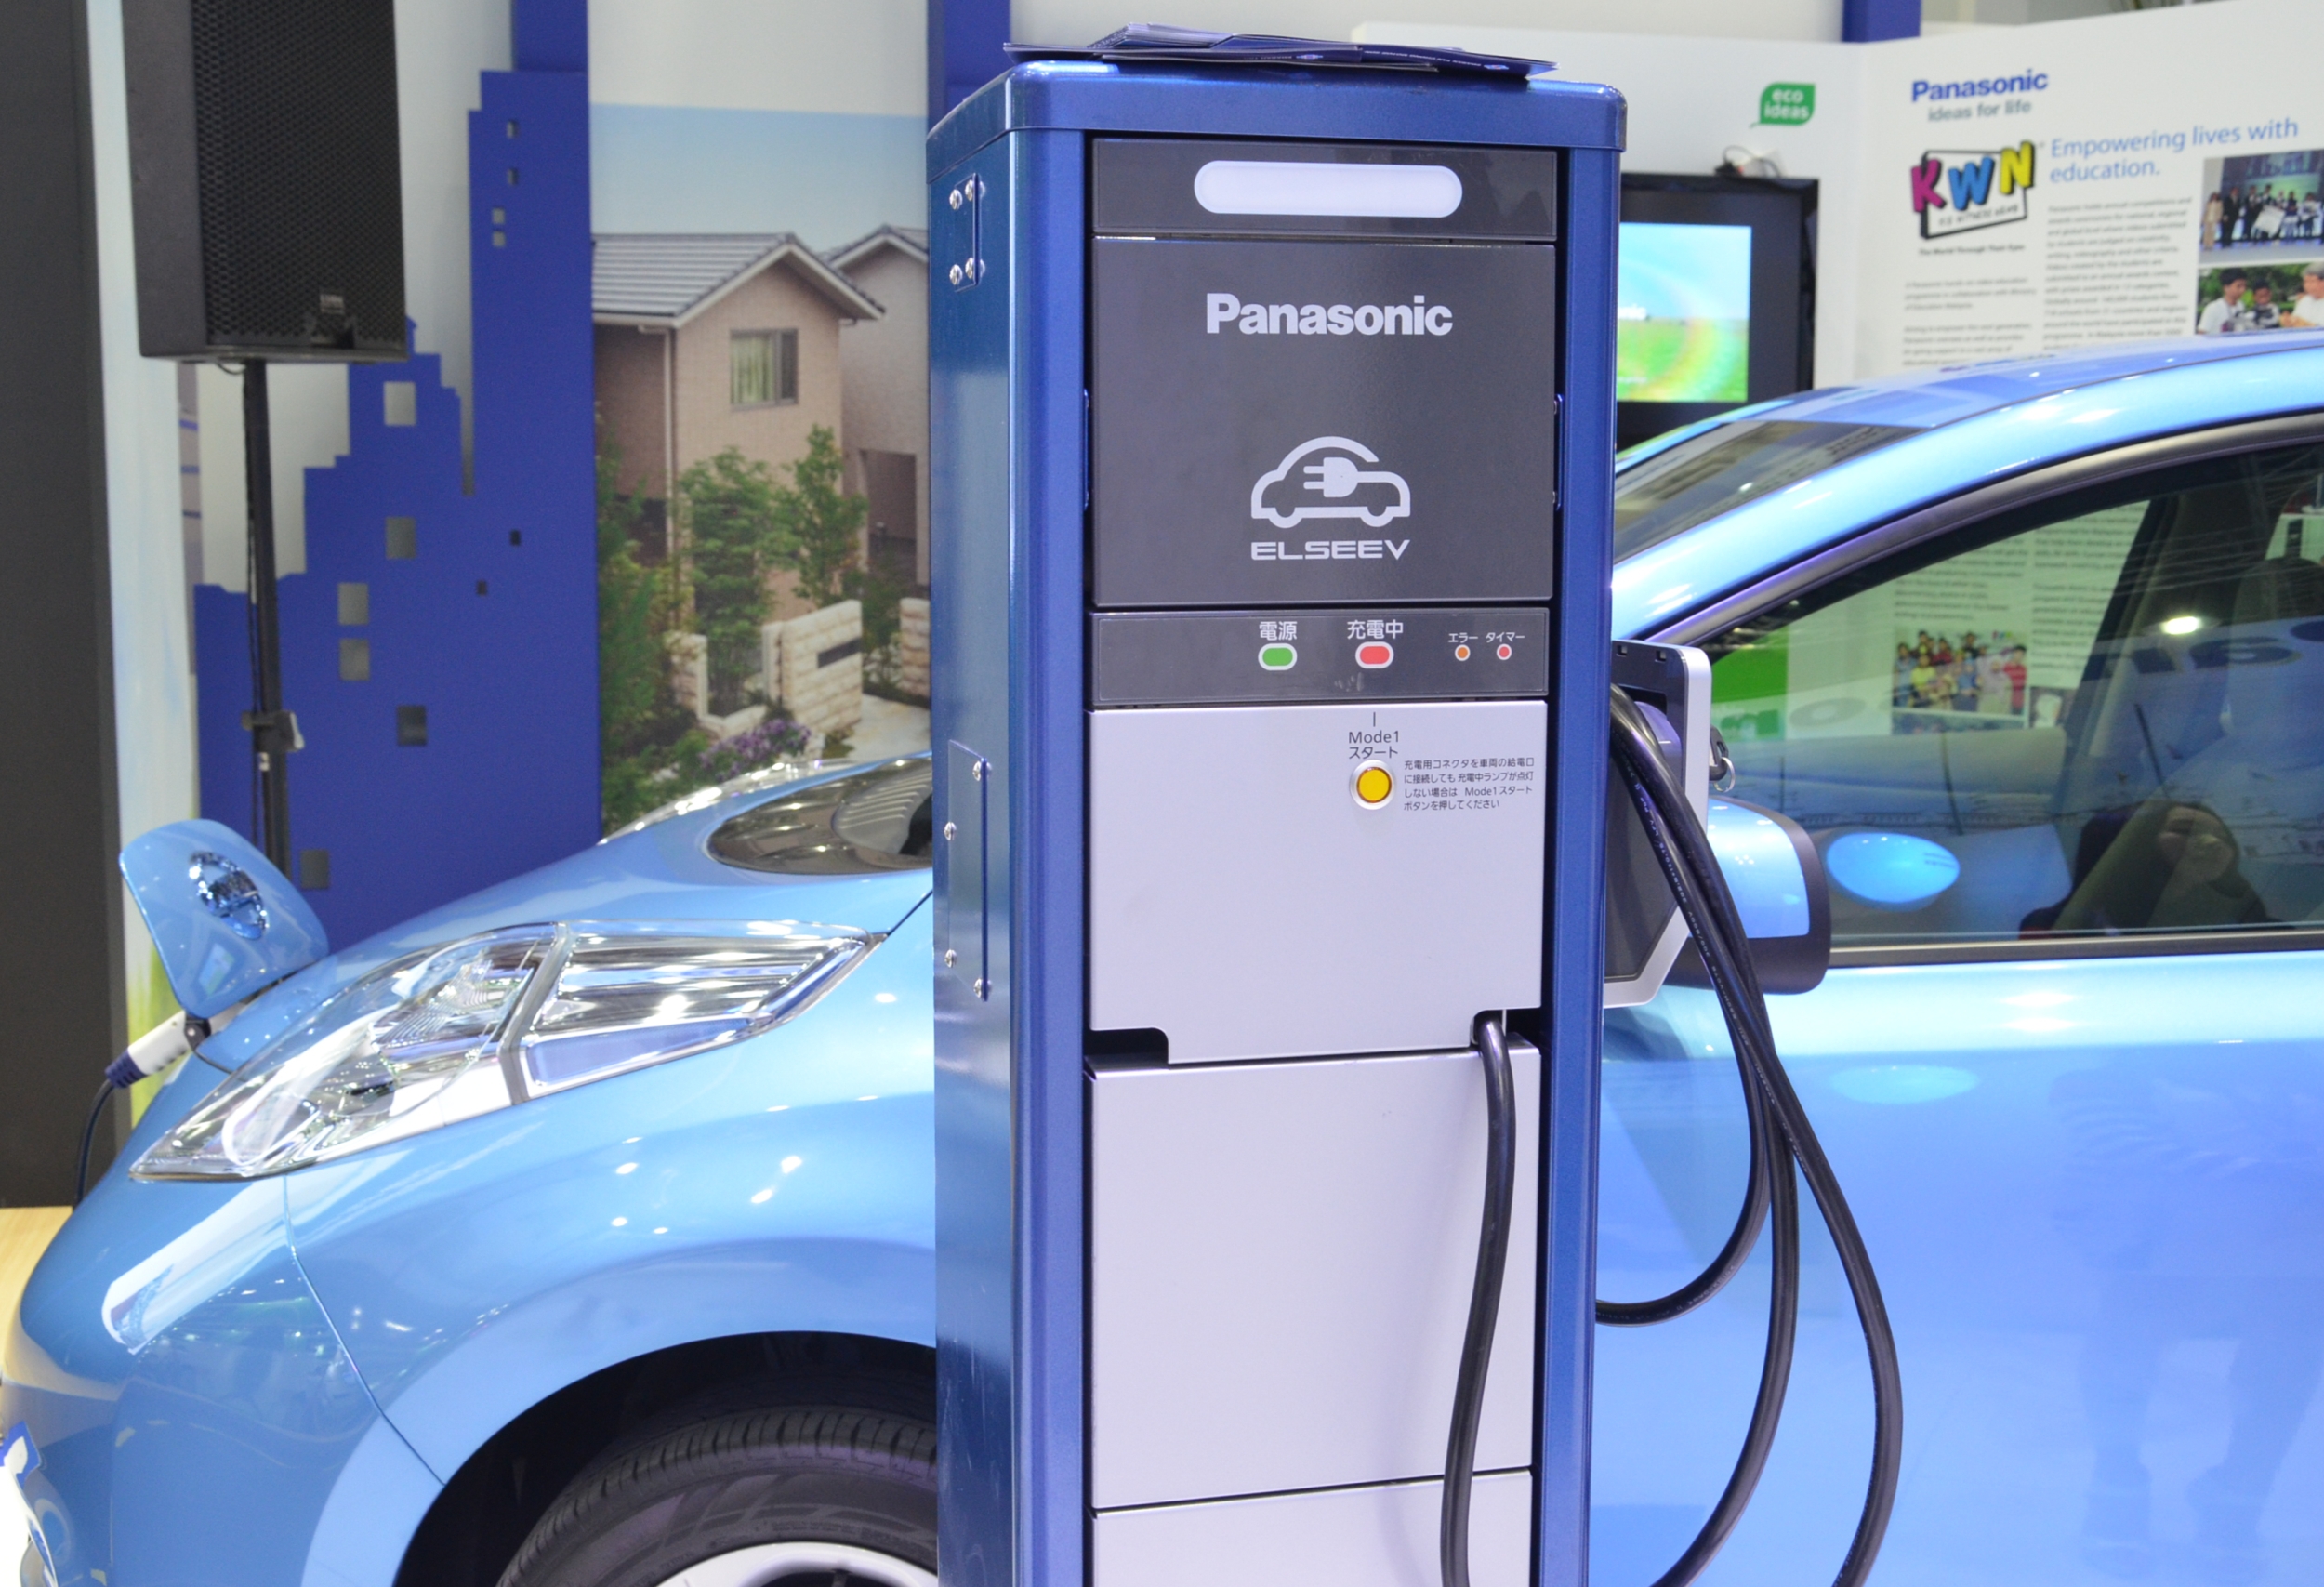
5G and electric vehicles are the next big things. I read that JHM plays some parts in 5G modules and EV charging stations which attracts my attention. 

However, its automotive-related LED back light business might suffer in Q2. Hopefully it can get back on track after that. 

125-150 EV charging stations to be built in Malaysia by 2017

I have sold all Notion shares to lock in the profit after holding it for more than 4 years. While its FY20Q1 loss-making result was not a surprise to me, I was a bit disappointed that the management did not mention much about its "Stingray" & "Nixon" projects.

I still have plan to buy back Notion, mainly due to its original business expansion while the new face masks business will be a bonus if it's sustainable. The management has warned that April & May will be the worst but expected a recovery in June. With the face mask business supposedly starting in June, may be it can help to save FY20Q2 result.

Matrix still haven't announce its FY20Q4 (Jan-Mac20) quarterly result yet, after being granted a delay until 15th July. Its results will be negatively affected but I'd expect worse result for FY21Q1 (Apr-Jun20).

Even though property market has slowed down for years, Matrix still registers increasing revenue and profit throughout the years. Its unbilled sales still stay at RM1.2billion at the end of Dec 2019. At least shareholders can expect consistent dividends for the next 1-2 years.

If not for the sales of industrial lands and total 5 quarters due to a change in financial year end in FY16, Matrix is a rare company which shows annual increasing revenue and profit without fail since listed in 2013.

Now we are already in the second half of 2020. So far this year I disposed 6 stocks and added 5 stocks. There are too many stocks in my portfolio now.

I nearly add another stock in June, but I hold back the strong buying desire due to depleted cash level. I need cash to subscribe to Jaks rights issue!


Wednesday, 9 March 2016

Property: Huayang, Tambun, Matrix

Most property stocks in Bursa Malaysia reversed their uptrend since Oct14.

Property stocks have been falling for one and half years now and I still do not see any encouraging signs of recovery.

Many property developers delay their new launches and registered poorer sales in 2015.

However, there are some who manage to take advantage of lower supply in the market to rake in more sales in 2015.

These companies are mostly those who serve a niche market with their exceptional branding or strategic location.

As I have less time for blogging, I will briefly review the quarterly financial results of those property stocks I have.

Currently I have 2 property stocks in my portfolio (excluding Scientex) after selling all Huayang shares in Jan16.


HUAYANG

Huayang's FY16Q3's financial result is good as expected.

It posted a PATAMI of RM30.2mil, with cumulative 9-month PATAMI of RM88.7mil which is 10% higher than FY15's corresponding period.


When I bought Huayang's shares in Sep14, even though I was aware of property market slowdown, I predicted that Huayang can post strong financial results for at least FY15 & FY16, and give at least 13sen dividend for 2 years.

This is actually not too hard to predict base on its previous new sales trend and unbilled sales.

If new sales manage to beat market expectation in FY15 & FY16, then the results could be even better.

Now we are at the end of Huayang's FY16 (which ends on Mac16), financial results and dividends are good as expected but there is no surprise in new sales.

EPS average about 11sen a quarter and what should be its fair value base on PE ratio?

Anyway, I failed to predict the PE ratio market would like give it.

This shows that PE ratio is nothing if market sentiment is poor in the sector.

New sales so far after 9MFY16 stands at RM255mil, which is unlikely to reach RM400mil in the whole year of FY16. Huayang achieves new sales of RM460mil for FY15.

So unbilled sales drop from RM733mil a year ago to RM530mil now.

It's not hard to predict that Huayang's FY17 will be poorer.

I have sold all my shares in Huayang at a loss of 13.3%. However, it does not mean that I don't like Huayang or it is a poor company. It's just part of portfolio management.

For FY16, Huayang should be able to give the same 13sen dividends like previous FY. This is a good 7.1% yield at current share price of RM1.82.


TAMBUN


Tambun posted a good FY15Q4 result but a fair value gain on investment property of RM6.67mil was included in the PBT.

Even though revenue drops 20% for FY15 compared to FY14, PATAMI manage to stay about the same at slightly more than RM100mil..

Just like Huayang, Tambun's new sales drop from RM429mil in FY14 to RM263mil in FY15. Unbilled sales drop from RM427mil to RM324mil in the same period of time.

However, I think this does not reflect the true sales status of Tambun as it was affected negatively by delay in development approval.

New project Raintree Park 2 contributed RM55mil new sales in Dec15, while Avenue Garden is still yet to be counted in.

I think these 2 projects (combined GDV RM300mil) should be able to give at least RM200mil of new sales to Tambun in FY15 if there is no delay.

Pearl City Mall, even though only a small 2-storey mall, will open to public in 2 weeks time. 

Besides, Jit Sin SPS branch should be able to start student intake for year 2017, and the plan to set up a private hospital in Pearl City is still on-going.

For 2016, new sales might not be that good but Tambun should not have a problem to surpass FY15's figure.

It should give around 9 sen dividend for FY15, which means a dividend yield of 6.8% at current share price of RM1.33.


MATRIX

Despite soft property market, Matrix still manage to sell more properties in 2015 which I think is rare in the sector.

Matrix bags a record-breaking RM805mil new sales in FY15 compared to RM630mil in FY14. Thus, unbilled sales also rise to RM633mil from RM429mil.


In FY16, Matrix will concentrate mainly on its Bandar Sri Sendayan, where it will launch projects worth more than RM1bil there in 2016.

It will build a new extreme park in BSS to make the township more appealing, while I think Matrix may end up operating a private hospital in the future.

Matrix has declared total 14.4sen (adjusted) dividends for FY15. This is a 6.0% yield at current share price of RM2.40.

Thursday, 19 November 2015

Matrix: Poor Result & Run!?

Matrix Concept FY15Q3 Financial Result

MATRIX FY15Q3 FY15Q2 FY15Q1 FY14Q4 FY14Q3
Revenue 121.4 120.4 317.6 151.0 148.8
Gross Profit 68.3 63.0 187.1 97.5 83.8
Gross% 56.3 52.3 58.9 64.6 56.3
PBT 40.2 41.4 155.4 73.8 58.5
PBT% 33.1 34.4 48.9 48.8 39.3
PAT 31.1 29.9 115.4 56.5 45.1


Prop Rev 116.7 117.1 315.5 150.5 148.8
Prop OP 41.6 45.2 158.4 77.6 61.2
Edu Rev 2.4 1.2 1.4 0.5 0.0
Edu OP -1.2 -2.1 -1.8 -2.9 -1.9
Club Rev 2.3 2.1 0.8 0.0 0.0
Club OP -0.3 -0.2 -0.6 -0.4 -0.4


Total Equity 808.9 774.2 758.3 686.0 643.5
Total Assets 1167.7 1129.6 1154.6 996.2 1000.9
Trade Receivables 148.6 149.4 192.6 79.5 174.9
Prop dev cost 649.5 597.2 583.5 566.2 556.3
Inventories 2.2 2.3 2.3 2.1 0.7
Cash -OD 52.7 75.7 84.3 58.7 23.3


Total Liabilities 358.9 355.4 396.4 310.2 357.4
Trade Payables 159.1 141.0 171.8 195.7 274.7
ST Borrowings 75.0 74.2 68.8 42.3 23.6
LT Borrowings 74.2 75.8 82.3 35.8 21.4


Net Cash Flow -5.7 17.3 25.8 -10.1 -45.5
Operation -6.2 11.2 -18.4 130.0 65.3
Investment -39.3 -33.4 -22.9 -93.2 -63.9
Financing 39.7 39.5 67.2 -46.9 -46.9


Dividend paid 66.8 47.1 17.1 77.6 60.5


EPS 5.90 6.50 25.20 12.40 10.50
NAS 1.47 1.67 1.64 1.50 1.41
D/E Ratio 0.12 0.09 0.09 0.03 0.03


Matrix's FY15Q3's result is flat compared to preceding quarter of FY15Q2.

However, it is significantly lower compared YoY to FY14Q3 mainly because of timing of billings.

Some people might be disappointed with this result.

What I am more interested in is how well it sells its property.


Despite a slowdown in property market in the whole country, Matrix actually does very well by bagging in sales of RM245mil in Q3 of FY15, with only RM8.3mil coming from industrial land sales.

For 9MFY15, its total new sales has reached RM612mil, which is 87% of its RM700mil annual sales target for FY15 (including industrial land sales).


Bandar Sri Sendayan alone has contributed RM519.7mil new sales in this period of time.

Unbilled sales surge to RM640.5mil (as at 30th Sep 15) from RM540mil a quarter ago. This should be its all time high quarterly unbilled sales.


New projects launched in Q3 include Suriaman 1 (phase 1 GDV RM77mil - 83% sold) & Hijayu Resort Homes (phase 1B) in BSS, and also Impiana Bayu 2 (88% sold) in TSI.

It seems like Matrix will not launch any new projects in Q4. It has delayed the launch of the RM229mil Residency SIGC to Q2 of 2016, may be because it sees no problem to hit its sales target in FY15.

Its high GDV condo near PWTC might be launched in the first half of 2016.

If you still think that Matrix's Q3 result is poor then just have a look at its year-to-date performance below.

       9-months comparison YoY: Improvement across the board


Matrix Global School has got 490 students enrolled as at end Sep15 and the management targets 660 students by end of 2015, which is revised downward from 800 students earlier.

Revenue from education arm increases progressively every quarter and its operating loss has narrowed.

Operation of clubhouse is also at loss but the main purpose of these two investment is to increase the selling point of its BSS.

Matrix continues its quarterly dividend payout with a 3rd interim dividend of 3.5sen. 

I think Matrix should be able to pay at least 15sen dividend for its FY15. So it might be another 4.5sen dividend after 10.64sen has been paid so far.

This translates into a dividend yield of 6.2% at share price of RM2.45.


For me, Matrix simply looks better than ever.

Tuesday, 11 August 2015

Matrix: A Little Surprise!

Matrix Concepts FY15Q2 Financial Result

MATRIX FY15Q2 FY15Q1 FY14Q4 FY14Q3 FY14Q2
Revenue 120.4 317.6 151.0 148.8 163.7
Gross Profit 63.0 187.1 97.5 83.8 74.6
Gross% 52.3 58.9 64.6 56.3 45.6
PBT 41.4 155.4 73.8 58.5 58.6
PBT% 34.4 48.9 48.8 39.3 35.8
PAT 29.9 115.4 56.5 45.1 42.4


Prop Rev 117.1 315.5 150.5 148.8
Prop OP 45.2 158.4 77.6 61.2
Edu Rev 1.2 1.4 0.5 0.0
Edu OP -2.1 -1.8 -2.9 -1.9
Club Rev 2.1 0.8 0.0 0.0
Club OP -0.2 -0.6 -0.4 -0.4


Total Equity 774.2 758.3 686.0 643.5 613.5
Total Assets 1129.6 1154.6 996.2 1000.9 944.5
Trade Receivables 149.4 192.6 79.5 174.9 160.0
Prop dev cost 597.2 583.5 566.2 556.3 524.4
Inventories 2.3 2.3 2.1 0.7 0.7
Cash -OD 75.7 84.3 58.7 23.3 29.4


Total Liabilities 355.4 396.4 310.2 357.4 331.1
Trade Payables 141.0 171.8 195.7 274.7 253.7
ST Borrowings 74.2 68.8 42.3 23.6 32.2
LT Borrowings 75.8 82.3 35.8 21.4 1.5


Net Cash Flow 17.3 25.8 -10.1 -45.5 -39.4
Operation 11.2 -18.4 130.0 65.3 68.8
Investment -33.4 -22.9 -93.2 -63.9 -55.7
Financing 39.5 67.2 -46.9 -46.9 -52.5


EPS 6.50 25.20 12.40 10.50 14.00
NAS 1.67 1.64 1.50 1.41 2.02
D/E Ratio 0.09 0.09 0.03 0.03 0.01


Matrix's FY15Q2 revenue and PATAMI drop 62% & 74% respectively compared to preceding quarter of FY15Q1!

They are even lower YoY compared to FY14Q2!

I guess all investors who follow Matrix closely should not be surprised by this result right?

This kind of result is already widely expected in fact.


After the bonus issue last month, I did think of whether I should sell some Matrix shares first as its share price will probably drop after "bad" Q2 result announcement, and I can buy at lower price later if I want to.

Anyway I did not do that, simply because I consider myself a "business owner" of Matrix.

Why should I sell my shares in this great company to others?

What actually surprise me a little is Matrix's latest unbilled sales.

Its unbilled sales stands at RM540mil at end of Q2 (Jun15), which is the highest level in 2 years.


The higher unbilled sales this time is due to more new sales achieved in FY15Q2 (RM210mil) and lower revenue recognition (RM120mil) in the same period of time.

The major contributor of this surging unbilled sales is from Bandar Seri Sendayan (BSS), in which the unbilled sales of projects there surge from RM264mil a quarter ago to RM427mil in FY15Q2.

No revenue recognition from land sales in current quarter though, as most have been rushed to be completed before GST last quarter.

New sales in 1H15 reaches RM367mil. So FY15 sales target of RM600mil (excluding industrial land sales) is well within reach.

Looks like Matrix's property is not too much affected by soft property market, just yet.


Matrix has launched RM437mil worth of new projects in the first half of 2015. It changed its plan to scale down targeted launch in FY15 from RM1.1bil to RM666mil. It will launch Residency SIGC with a GDV of RM229mil in Q3.

Planned project launch in 2016 include affordable housing project worth RM1bil in Kota Gadong Perdana next to Bandar Seri Sendayan.

This huge project comprises 3200 units of houses priced below RM400k, and should be able to help Matrix to sustain sales in FY16.

Both the school and clubhouse still register operating loss in this early stage of operation.

There are 450 students in Matrix Global School as at mid-2015, compared to 320 in the end of 2014.  The figure has reached 500 in August. Matrix targets 800 student by year end.

Besides, Matrix has just incorporated a new company Matrix Healthcare Sdn Bhd, which is believed to provide healthcare services in BSS in the future.

Matrix declares a 2nd interim dividend of 3.5sen per share. It has a policy to pay out at least 40% of its net profit.

I expect at least 15sen dividend for FY15.


Matrix's PATAMI should be able to reach at least RM200mil for FY15. With about 542mil shares at the moment, its projected EPS will be 37sen.

Its forward PE and DY will be 6.0x and 6.7% at current share price of RM2.23.

Long term investors in Matrix should focus on its business, not its share price.