Showing posts with label SP Setia. Show all posts

Thursday, 26 September 2013

Eco World & Liew Take Center Stage

Recently we can see Eco World's advertisement all over the place, billboards, radio, newspapers etc. Eco World might be a new comer in the property development scene, but they come with vast experience in this field and they will be aggressive in the market.

Eco World's CEO Dato Chang Khim Wah, directors Dato Leong Kok Wah & Tan Sri Abdul Rashid all jumped ship from SP Setia. Another young director Liew Tian Xiong is the son of current SP Setia's CEO Dato Seri Liew Kee Sin.


Recently on 17th September 2013, Eco World and one of its director Liew Tian Xiong has entered into a conditional share sale agreement with multiple shareholders of main board listed property developer Focal Aims, to acquire 164,775,701 shares (65.05%) of Focal Aims for a total cash of RM230.7mil (RM1.40 per share).

If this acquisition go through, Eco World as a new major shareholder has to make a mandatory offer of RM1.40 to other shareholders in Focal Aims.

Focal Aims net asset per share stands at RM1.26 from its latest financial period ended 30th June 2013. Its share was traded between 60-70sen before the news broke out. Now it has reached over RM2.

Liew Kee Sin's time in SP Setia is going to end soon, and it is not hard to predict where he will land next.

Eco World just launched its maiden project EcoBotanic in Nusajaya, Iskandar Malaysia. Its initial launch include 624 units of cluster & semi-D houses which are priced at RM900k - RM1.3mil & RM1.8 - RM2mil respectively. They are all luxury things and do not come cheap. Nonetheless, it was reported that those 500 units allocated to non-bumi were snapped up in 6 hours. 

EcoBotanic covers a 118.8ha site and has a GDV of RM3 bil which will be developed over 8 years.


       EcoBotanic: Next to industrial park & highway? Who cares?

       EcoBotanic: Power lines in the vicinity? Who cares?

You think it is a not so "eco" EcoBotanic? Who cares? It has SP Setia's DNA. Yes, this is what people care nowadays.


       Location of EcoBotanic within Iskandar Malaysia

Other projects that queue up at Eco World include the RM1.2bil EcoSky in Taman Wahyu KL and a new 246ha township in Tebrau Johor. EcoSky is expected to be launched in the final quarter of 2013 while development at Tebrau should start in 2nd quarter of 2014.

Eco World says that it has a total of 3,000 acres landbank located at Johor (1913 acres), Klang valley (1080 acres) & Penang (60 acres) with a total GDV of RM30 billion. Recently it works with Salcon to develop a RM1.2 billion mixed commercial project JB Festival Mall & Serviced Apartments in Johor Bahru. Salcon's executive director Leong Kok Wah is also Eco World's director.

Tropicana has about 2,300 acres of landbank including the recently purchased Pulai land. This means that Eco World has more landbank than Tropicana.

However, it is reported that Tropicana's total GDV stands at RM70 billion (excluding Pulai land). Wow! Can you believe it?

Thursday, 5 July 2012

Malaysia 1-0 Chelsea FC

SP Setia (40%), Sime Darby (40%) and EPF (20%) has just successfully clinched the rights to redevelop a 39-acres Battersea Power Station site in London for 400mil pounds. The piece of land south to the River Thames, is said to be the last piece of prime land in central London available for redevelopment. 

      Battersea prime land

One of the many bidders for the site is Chelsea Football Club, who may wish to have a new ground there. The existing ground Stamford Bridge is just opposite the river. Now Chelsea FC has lost before the start of new season...

     Battersea power plant

After Singapore and Australia, SP Setia has successfully placed its footprint in another developed country. With the experience and capability of SP Setia & Sime Darby, this redevelopment should be a success.

Malaysia's Chelsea FC fans may wish to get a holiday home there!

Friday, 20 January 2012

Win-Win in SP Setia

Now, the CEO and founder of SP Setia, Liew Kee Sin, has become an "offeror" in the takeover of SP Setia by PNB.

      Liew Kee Sin

This is the result of a revised deal whereas in earlier deal, Liew have to give up his 8% stake (158.2 million shares) in SP Setia to PNB. After the revised takeover, Liew will now hold on to his stake and continue to lead the company. Liew will be given a put option to sell his shares at the takeover price to PNB in three years time after the takeover, if he feels the need to do so.

As a result of the revised deal, the takeover price has increased 5 sen from previous RM3.90 to RM3.95 per share, while the warrant price will be revised to 96 sen from 91 sen. Thus, minority shareholders should be happier.

At last, they live happily ever after.. The End.

Tuesday, 4 October 2011

More Land for SP Setia

After the acquisition of a 404 ha land in Ulu Langat for a mixed township development worth RM3.5bil, SP Setia has just announced its intention to acquire another piece of land in the area. The said land with a size of 269.3 ha is just adjacent to the earlier acquired land, which is located at Rinching, somewhere between Semenyih, Bangi old town and Beranang. This add up to a total land area of 673.3 ha.


     Possible location of new SP Setia land at Ulu Langat

After the tremendous success of Setia Alam/Eco Park township, SP Setia is planning to duplicate the success in this new township at the Kajang-Semenyih corridor. The place is very near to Negeri Sembilan. Previously people may say that Semenyih is "ulu" and Bangi is too far from KL to have any significance in term of property investment. But now, the tide has come to these area, and also perhaps Dengkil, Banting, Sepang in the near future.

Can SP Setia successfully transform the land into a thriving and happening township? I believe that it can, with its track record, strong financial background, supreme brand name and the link with the government.

The property sector is poised for a downturn in the near future, I wonder when will SP Setia launch the first phase of this new development. The residential units in the township is said to be more "affordable" with the aim to let first time house buyers owning a house. Anyway, if it is going to launch now, I think the respond should still be overwhelming, with people queuing overnight. What to do? It's SP Setia.

    Setia Alam Township

Wednesday, 28 September 2011

SP Setia Is The Next Target

 
Seems like the Malaysia government is trying to take control on major property developers. After the successful merger of UEM Land and Sunrise, failed merger between MRCB & IJM, proposed deal between Sime and E&O, now SP Setia, one of the country's best developer, is the next target by government linked fund or company.

Today Permodalan Nasional Berhad (PNB) proposed to take over SP Setia at a price of RM3.90 and its warrant at RM0.91. This represents a premium of 40sen (11%) on its mother share and 45sen (98%) on its warrant. There is a "wow factor" on its warrant!

This explains why both shares surged massively on high volume yesterday, after weeks of free falling, where SP Setia rose 13% and and SP Setia-WB rose 21%. Today both shares are suspended and we can expect another surge tomorrow when they resume trading.

Government-linked funds PNB, EPF and KWAP collectively owns 47% of SP Setia's share. This is just a proposal. Will the take over be successful? Or will it end up like MRCB-IJM? Will SP Setia be privatized?

When the government takes some control in property developers, may be the launch of new projects and the rise in property price may slow down a bit.
 

Tuesday, 26 July 2011

SP Setia wants 100% KLEC

    KLEC: official launch in August?


KUALA LUMPUR: Maybank Investment Bank Research is reiterating its Buy on SP SETIA BHD [] and raise the target price to RM5 after it proposed to acquire the remaining 40% stake in KL Eco City (KLEC).

“We are excited on SP Setia's purchase of the remaining 40% stake in KLEC. This non-cash acquisition will immediately boost SPSB’s earnings by 0.6% to 1% and RNAV per share by 8.0 sen,” it said on Tuesday, July 26.

Maybank Research said all it would cost SP Setia would be 19.4 million new shares, which is a mere 1.1% increase of its existing share base.

“We upgrade our forecasts by 0.3-1.9%. Reiterate Buy with a higher RM5.00 target price (+24 sen; 10% premium to RM4.53 RNAV).

SP Setia proposed to acquire the remaining 40% stake in KLEC from Yayasan Gerakbakti Kebangsaan (YGK) for RM75 million.

Derived from a discounted cashflow valuation range of RM53 million to RM73 million, it said the RM75 million implied RM187.5 million equity value for the project.

The purchase price will be funded via a 19.4 million new share issuance (1.1% of existing share cap; RM3.87 issue price, 1% below Monday’s close).

YGK, a foundation owned by UMNO Youth, is established to administer funds for the eradication of poverty and enhance the welfare of the poor. The acquisition is expected to be completed by end-2011.

Maybank Research said apart from having a full control of KLEC, this non-cash acquisition will also save working capital for KLEC’s infrastructure works, CONSTRUCTION [] of MOH buildings in Setia Alam and Fulton Lane in Melbourne.

“Elsewhere, SP Setia has thus far achieved a stunning RM1.9 billion sales in 8MFY11. This excludes RM1.6 billion to RM1.8 billion bookings/sales of KLEC’s strata and boutique offices as well as Residential Tower One, which could potentially boost SP Setia’s sales beyond its initial RM3 billion target for the year.

“We understand that SPSB intends to launch KLEC in August after the final approval from Unit Kerjasama Awam Swasta (UKAS) is obtained,” it said.

Saturday, 16 July 2011

SP Setia: Selling Climax triggered?


Since the interim dividend of 5 sen was ex-ed in 6th June, SP Setia's share price enter into a free fall mode.

There is no particular bad news on SP Setia, I guess. However, world market is generally bearish and the overall property segment outlook is reported by "someone" to be "cautious" recently, especially for high-end property. Today, a report emerges: "SP Setia falls to March low, CLSA downgrades", and SP Setia's share price fell the most in recent days (closed 12sen down and recovered from once 23 sen down), along with Mahsing (down 8 sen).

A massive intraday fall with a significantly higher volume in a significant downtrend. Could this mark (at least temporaril) the end of the downtrend or a "selling climax"? Technically speaking, its share price could stage a rebound next week. However, how long the rebound will sustain depends very much on the overall market sentiment. Don't forget the overall world market is still gloomy at this stage.

    Selling climax marks a trend reversal?

How is the future of SP Setia? Can it give us a steady revenue and profit growth at least for the next 2-3 years?

I've checked their website and found an interesting and useful presentation put up in June. Here are some of the slides.
After 6 months, net profit rises 70% from RM89.4mil to RM154.2mil, with a 30% revenue growth. The EPS is very much diluted after the 1:2 bonus issue in April. Perhaps this makes SP Setia less attractive now?

SP Setia is currently in a slightly net cash position, that's good. However, the ROE is not very good. It pays out 60% of its profit as dividend!

A glance of SP Setia's active projects. The unbilled sales are at RM3.2bil.

There are a lot of land that are still yet to be developed, especially central region with a remaining GDV of RM29.46bil?!

The 268 acres Eco Glades: The next Setia Eco Park? Will this high-end thing attracts the heart of those expatriates there in Cyberjaya?

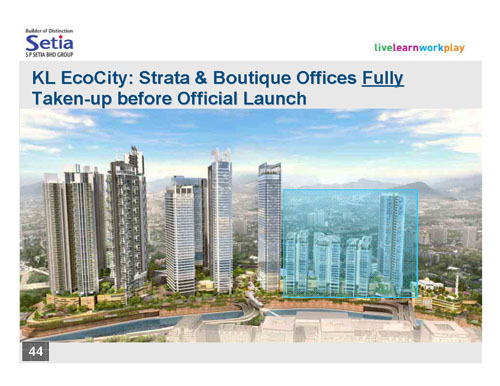
KL Eco City should be SP Setia's next gold mine. The office block if not mistaken was sold en-bloc. One of the residential block just pre-launched in June. Anyone know how is the response?

Development in Vietnam encounters a set back and might be slow at the moment, but I believe Vietnam will experience the growth like what Malaysia has in the 1990s. Multinational company's focus will shift there soon.

SP Setia's first in Australia, the Fulton Lane apartment in Melbourne was 70% sold during its preview in Malaysia last month. It's a preview only, and grabbed by Malaysian investors.

GDV RM318mil Singapore project is pending approval.

Target total group sales for FY2011 is RM3bil. So ambitious. It achieves RM1.6bil for the first 7 months. Can it get another RM1.4bil in the next 5 months?


At RM3.89, is SP Setia worth to invest in?

I actually do not intend to buy any shares at this moment, but I can't help this time and bought some SPSETIA-WB on friday late afternoon. May be for short term play only, as it has a high possibility to drop further. US/Europe end the week with a little bit of optimism, though still surrounded by negative news.

Monday, 11 July 2011

Bayan Mutiara: Ivory vs SP Setia

Ivory's share surged last week as Penang Development Corporation is going to announce Bayan Mutiara 24.8ha land award in Penang south-east coast this week. There are only 2 bidders, which are Ivory and SP Setia.


Last week, Ivory's share price rose almost 20% but SP Setia's share price fell almost 3%. Seems like the result is already known???

Pros for Ivory:
  • Penang base developer
  • "Reported" to have submitted a higher bid of RM200psf (rumour?)
  • SP Setia just rewarded the sPICE project in January. Is it possible to get another in a short period of time?
  • Ivory's share price up last week, why not SP Setia's?
Cons for Ivory:
  • SP Setia is best developer in the country
  • SP Setia still has no development in the hot south east coast
  • Ivory's recent Penang Time Square is a failure (I think)
Both are good companies, way better than those RM1 "empty" companies which used to get this kind of project  in the past. Both have the ability to come out with an impressive development. So I think the higher bidder will get it (Penang needs money!).

P/S: stock alert on SPSETIA-WB