Wednesday, 11 December 2013

More Excitement In Seberang Perai Selatan

Mahsing officially joins Seberang Perai property feast by acquiring 76.38acres of freehold land in Jawi for RM42.6mil, or RM12.80 psf.

The land which is said to be opposite the Bukit Jawi Golf Resort, will be developed into a mixed township with an estimated GDV of RM400mil known as Southbay East.

Southbay East... It is quite confusing with its Penang island development, isn't it?

The location of the land should be very close to IJM Land's recent acquisition in Jawi (70 acres at RM18.50 psf).

Ecoworld (60 acres at RM30 psf) and Tambun Indah (24 acres at RM14 psf) recent land purchase is at a totally different area, which is close to Tambun toll, while IJM & Mahsing's land are close to Jawi toll.


With two powerful developers in Jawi, it is expected that the roads connectivity of this area to Batu Kawan & Penang Second Bridge will be improved. Currently if you wish to go to Batu Kawan or second bridge from Jawi or Nibong Tebal area, you need to enter North-South Highway via Jawi toll and exit the upcoming Batu Kawan toll.

If you do not want to pay for the toll, you need to travel a long way north to Tambun area, which is not worth the time and petrol money spent. In the future, there might be a route joining Changkat area (between Jawi & Nibong Tebal) to the south of Batu Kawan.

For me, the location of Mahsing's land is the least strategic among all 4 developers mentioned. It is like in the middle of nowhere. If other ABC developer wish to launch high-end project there, I guess it will have a hard time selling it.

I estimate that a standard size double storey terrace in a gated community in this area should be about RM300k. If Mahsing is going to launch the project now, RM400k a unit is not a surprise. However, Southbay East is expected to be launched only in year 2015.

Since it is Mahsing who has a lot of fans and builds premium quality homes, surely it will not face a big problem selling its products there.

       Bukit Jawi Golf Resort

What I am more concern is, how will the recent influx of branded property developers into mainland Penang affect Tambun Indah's Pearl City?

From experience, township planning & ability to attract business investment point of view, I think Tambun Indah may lose to Mahsing, IJM and Ecoworld.

The advantages that Pearl City has include big land size, location and overall lower land cost, which translates into more competitive selling price.

Fortunately for Tambun Indah, the lands owned by the other 3 developers are not very big and can't be developed into a true mixed township that include shopping complex, medical center or large commercial area. So this is an advantage of Pearl City.

However, Tambun Indah may not have the same ability as Mahsing & IJM in attracting good business investment into its Pearl City business park.


       Proposed Pearl City Mall

Secondly, the location of Pearl City is closer to Bukit Mertajam and those many industrial parks in Seberang Perai Tengah such as Penang Science Park, Bukit Minyak and Perai. Ecoworld shares the same benefit but Mahsing and IJM don't.

In term of distance to Batu Kawan & Penang Second Bridge, all are quite similar but Ecoworld and Tambun Indah have the slight benefit of no need to pay for extra toll.

Ecoworld, IJM and Mahsing surely will build gated & guarded communities which are likely to be priced higher. Thus, Tambun Indah who build gated and non-gated community, can have more flexibility in its pricing.

For me, Tambun Indah will get better if property outlook in Seberang Perai Selatan gets better.

Asas Dunia is another major mainland developer that should not be overlooked, although it has been privatized. It has lots of land in Seberang Perai Selatan bought at very low cost and also starts to build better quality houses to target middle income group. Thus, Asas Dunia is probably the ultimate winner in Seberang Perai Selatan property boom.
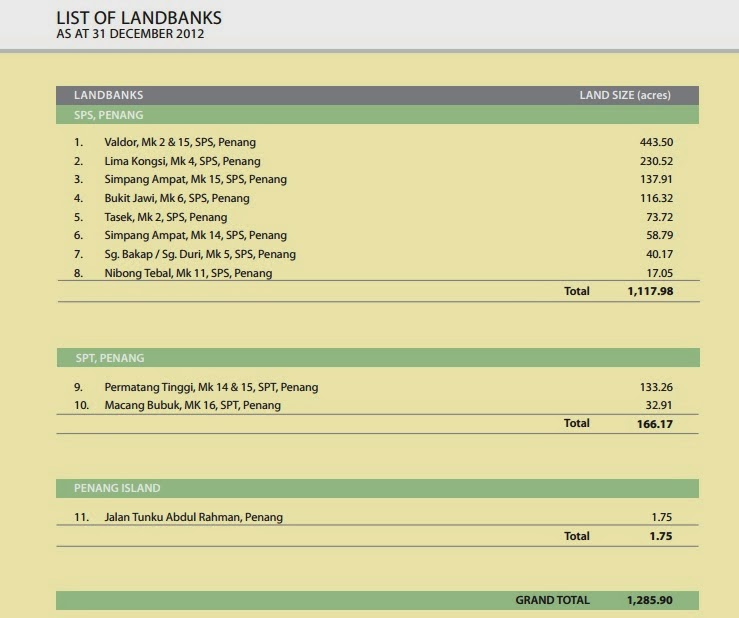
       Asas Dunia: 1,118 acres land in SPS


Tuesday, 10 December 2013

BJAuto: Zoom-Zoom To The Sky

If I had known BJAuto's FY14Q1 results (May13-Jul13) earlier, surely I would have applied for its IPO.

I only knew it after BJAuto released its FY14Q2 financial result last week.

For FY14Q2 (Aug13-Oct13), BJAuto's quarterly revenue and net profit rise 30% and 250% YoY to RM282.4mil and 27.6mil respectively.


BJAuto FY14Q2 FY14Q1 FY13Q4 FY13Q2
Revenue 282.4 428.4
217.3
PBT 37.5 36.2
10.9
PBT% 13.3 8.5
5.0
PAT 27.6 26.1
7.9


MAS Rev 635.2


MAS PBT 62.4


PHI Rev 75.7


PHI PBT 6.0


Total Equity 211.8
158.8
Total Assets 425.8
485.5
T/Receivables 68.1
47.0
Inventories 120.8
193.8
Cash 166.5
182.0 52.9


Total Liab 205.1
319.4
T/Payables 109.7
124.1
ST Borrow 6.4
126.6
LT Borrow 0.0
2.4


Net CF -15.5

-24.4
Operation 107.3

-71.7
Investment -0.1

-18.0
Financing -122.7

65.3


EPS 3.83

1.1
NAS 29.42
22.06
D/E Ratio Net C
Net C


For 1HFY14, its revenue and net profit rise 65% and 162% to RM710.9mil and RM53.7mil compared to previous FY corresponding period. In the first half of FY2014, its net profit has already surpassed previous full FY figure of RM52mil.

From here, we can work out BJAuto's FY14Q1 result, which is RM428.4mil revenue and RM26.1mil PAT.

Compared to FY14Q1, BJAuto's FY14Q2's revenue drops 34% due to supply issue in Malaysia. However, improved margin & sales mix push its PAT up to beat Q1 marginally.

The overall increase in revenue is due to better sales of CX-5 and Mazda 6, contribution from Philippines which started since Jan13 and much better profit margin. The phenomenal increase in profit is also partly contributed by its associated company MMSB which runs the CKD project starting from Feb13 (PBT RM4.7mil in 1H).

Though car sales in the end of any calendar year is generally slower, but it should be strong in the beginning of the year. So if we annualized 1HFY14 PAT, it will give an estimated FY14 PAT of about RM110mil for BJAuto. With this result, estimated EPS will be 13.7sen (802.8mil shares). 

Since BJAuto is expected to register further growth in 2H14 especially when the 2014 Mazda 3 is launched, I think a target PE ratio of 15x is quite fair. This will give BJAuto a fair value of RM2.05.

At the same time, BJAuto declares its first interim single tier dividend of 1.75sen. 


Another thing noteworthy is that BJAuto has repaid its borrowings by as much as RM140.7mil in 1H14, thus paring down its borrowing substantially from RM126.6mil six months ago (30 Apr 2013) to only RM6.4mil on 31 Oct 2013. Its cash plus bank deposits just fall slightly from RM182mil to RM166.4mil in the same period of time. All these are achieved by using cash from operation even before its IPO in November.

In another words, BJAuto has a very healthy balance sheet indeed, and will be further boosted by RM58mil cash from IPO from FY14Q3 onward.

BJAuto's  IPO price is just 70sen. Just 3 weeks after its listing, its fair value suddenly jumps to RM2. Who the hell is setting the IPO price?

Now the big jump in its share price on its debut day seems to be well justified...

Saturday, 7 December 2013

Enterprise Value

Market Capitalization can be used to determine how much a company worth at a point of time, or "how big" a company is. However, there is a more accurate measure of a company's value, which is the Enterprise value.

The calculation of Market Cap is quite straight forward,

Market Cap = Share Price x Total Outstanding Shares


Enterprise Value (EV) is also not hard to calculate,

EV = Market Cap + Debt + Minority Interest + Preferred Shares - Cash & cash equivalent

All the figures except market cap can be obtained from the balance sheet.

EV is a theoretical takeover price. It is widely considered as a more accurate representation of a company's value.

When company A wishes to takeover or acquire company B, it needs to:

  • pay company B's ordinary shares holders (market capitalization)
  • pay company B's total debt
  • pay company B's minority interest shareholders
  • pay company B's preferred shares holders

However, company A does not need to pay for company B's cash. It will pocket the cash.

After obtaining the EV, we can calculate a company's Enterprise Value Multiple (EVM), which is one of the investment valuation ratio like the more commonly used PE ratio.

EVM = EV / EBITDA

EBITDA = Earning Before Interest, Tax, Depreciation & Amortization


EVM roughly tells how long it would take for an acquisition to earn enough to pay off its cost, assuming that there is no change in its annual EBITDA.

If EVM is 10, then it will take 10 years. Thus, the lower the number the better it is.

EVM might be a better valuation ratio compared to PE ratio as it includes a company's earning, debt and cash into the valuation, while PE ratio is only about a company's earning.

Like any other financial ratios, it is best to compare with peers and historical data.


Friday, 6 December 2013

Car Electronics Maker Builds Hospital

Multico is one of the stocks in my stock alert list. It caught my attention because of its low PE ratio and good dividend yield. It is in Cold Eye's 42 stocks list as well.


Multi-Code Electronics is a Johor-based manufacturer of vehicle electronics parts founded in 1990. It has now grown to become a leading Original Equipment Manufacturer (OEM) specializing in full spectrum of design, manufacture and supply of automotive electronics and mechatronics parts for the Malaysian and regional markets.

In Malaysia, it has Proton & Perodua as its clients with long-term contracts to supply various car electronics parts such as reverse sensors, functional switches, key sets, actuators, power window regulators, anti-theft system etc.

Though the national cars contribute to a vast majority of its business, Multico also supplies parts to Honda in Melaka and Ford in Thailand & Australia.

Multico's revenue has been flat for the past four years (FY10-FY13 end July) between RM100-110mil. From its recently announced financial result, full-year FY2013 revenue falls slight from RM111.1mil to RM109.2mil, but net profit rises from RM11.1mil to RM28.9mil.

Multico Financial Result FY09-FY13

RM mil Revenue PAT
FY09 84.7 0.2
FY10 103.7 9.4
FY11 101.6 8.7
FY12 111.1 11.1
FY13 109.2 28.9


In FY13, there is a one-off gain of RM19mil from the recovery of doubtful debt arising from the legal actions and proceedings against its certain former directors and subsidiaries.

Without this special gain, I think Multico's net profit for FY13 should be around RM11.5mil, which will still break its previous year's record of RM11.1mil by a thin margin.

At this estimated FY13 earning of RM11.5mil, Multico's EPS will be 25.9sen base on 44.4mil shares. This will give it a PE ratio of only 6.4x at current share price of RM1.67. A fair PE of 10x will give it a fair value of RM2.59.

Multico gave away 12sen of net dividend for its FY2013, representing a net yield of 7.2% at share price of RM1.67. However, 6sen of it is a special dividend due to the special gain. Thus its future expected dividend yield is about 3.6% (6sen).

       Functional Switches

In mid November, Multico made an announcement to purchase a 3.3acres commercial property within Setia Alam for RM28.6mil to build a healthcare facility. 

What? A car electronics manufacturer diversifies into provision of healthcare services?

The first question that comes to my mind is, is any of the directors or major shareholders a medical doctor?

Yes, true enough. After checking through the directors profile, Multico's executive director and single largest shareholder Goh Kar Chun holds a medical degree from Ireland. He worked as a medical doctor for 2 years  in Ireland before joining the company. 

Apparently he made a wise decision in joining Multico. He is only 37 years old now.

However, in my opinion, I don't think the decision to build hospital will benefit the shareholders in the near future. Establishing a hospital is neither cheap nor easy. It needs a lot of money and experience. It may require a joint venture with an experienced partner.

The construction of the hospital building will only commence in year 2015 and is expected to be completed in 2018. So during these years, I would expect Multico's earning to be under pressure due to the cost involved. 

Furthermore, when the new hospital starts to operate in 2019, usually it will register loss in its early years due to lack of customers and high staff cost.


       Goh KC & Lim MK

Without this healthcare diversification, Multico's core business seems to be quite stagnant for the past few years. The management has a plan to expand regionally especially into Indonesia & Thailand. I'm not sure how's the progress now.

Back in July, Multico has signed a joint venture agreement with an Indian party to manufacture and supply automotive parts in India. However, there is no further announcement made until now.

I believe the overall automotive industry will grow in the near future. However, national cars may face stiff competition from other car makers.

Even though it is traded at relatively low PE, it is very unlikely that I will invest my money into it in the near future. So, I'll remove it from my Stock Alert List.

Fundamentally, Multico is still a good company with some growth potential in its core business.